Understanding Sterling: The UK Currency and Everyday Banking Basics
Part of the Paul Beare UK Expansion Knowledge Hub.
Sterling itself isn’t complicated. Pounds and pence, same as any currency. What catches overseas companies out is everything wrapped around it: sort codes instead of routing numbers, a Faster Payments system that clears same-day when SWIFT would take three, and a bank account application process that can take high street banks six months or more if you’re a director based overseas.
None of this is a reason to delay opening a UK account. It’s a reason to understand the landscape before you start, so you’re not four months into an application wondering why nothing’s moved, or paying SWIFT fees on every payment when a local account would have settled the same transaction for a fraction of the cost.
This post covers the everyday basics: how sterling and UK payment systems actually work, what opening a business account as an overseas company involves, and where the real friction tends to show up.
What Sterling and UK Banking Actually Involve
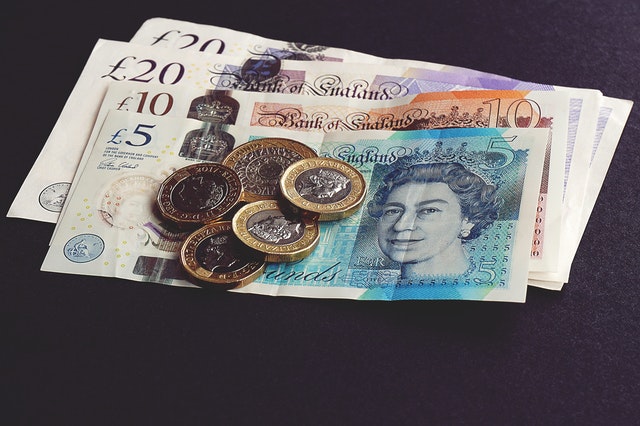
Sterling, GBP, is the currency used across England, Scotland, Wales and Northern Ireland, with no regional exchange rate or variation. Scottish and Northern Irish banks issue their own banknotes, which sometimes confuses overseas visitors, but the currency and its value are identical throughout the UK.
Where UK banking differs from many other markets is in its plumbing. Instead of a routing number, UK accounts use a six-digit sort code alongside an account number. Domestic payments mostly move through Faster Payments, which typically clears within hours rather than days, a genuine improvement on the multi-day SWIFT transfers many overseas companies are used to for cross-border payments.
For a UK-registered company, having a GBP account isn’t optional in practice. HMRC expects payments and filings in sterling, staff and suppliers expect to be paid in sterling, and clients paying into a foreign currency account adds friction and cost that a local account removes.
Why It Matters for Overseas Companies
The banking step is where a lot of overseas expansions actually stall, not the company formation itself. Filing paperwork with Companies House is straightforward. Getting a bank willing to open an account for a company with no UK trading history and a director who isn’t UK-based is a different problem entirely, and traditional high street banks can take several months to reach a decision, sometimes longer.
The cost side matters too. Businesses relying on SWIFT transfers for every UK payment typically pay a percentage-based fee on each transaction and lose time to multi-day settlement, and that adds up quickly for a company making regular payments to UK staff, suppliers or landlords.
Neither problem is unusual, and neither should be a reason to delay entering the UK market. But going in without knowing the timeline and cost realities means budgeting and planning around an assumption that turns out to be wrong.
How It Works in Practice: Opening and Running a UK Account
A UK business bank account typically requires a Certificate of Incorporation, details of directors and shareholders, proof of a UK business address, and identification for company officers. High street banks generally want more of this in person and take longer to process applications from companies without a UK-resident director, often several months.
FCA-regulated digital providers offer a genuinely faster alternative, often opening an account within days once documentation is submitted, with a UK sort code and account number, access to Faster Payments, and multi-currency capability that lets a company hold and convert GBP, USD or EUR without repeated conversion fees.
Once the account is open, day-to-day running is straightforward. Faster Payments handles most domestic transfers, CHAPS covers same-day high-value payments, and standing orders and direct debits work the same way they do for any UK business, covering everything from payroll to recurring supplier payments.
What Overseas Businesses Should Know
Start the bank account process early, ideally in parallel with company formation https://www.paulbeare.com/uk-company-formation/ rather than after it. Treating banking as a sequential step after registration is the single most common reason overseas companies lose weeks or months they didn’t need to lose.
Decide early whether a high street bank or an FCA-regulated digital provider suits your situation better. High street banks carry more traditional credibility with some UK counterparties, but the approval timeline is genuinely longer for overseas-directed companies. A digital provider gets you operational faster and is now widely accepted by UK clients, suppliers and landlords.
Factor exchange rate exposure into your planning from day one if your parent company is funding UK operations from overseas. Holding a GBP balance and converting in planned batches, rather than on every individual transaction, generally reduces both fees and the impact of currency movement on your UK budget.
Common Mistakes International Businesses Make
The most common mistake is assuming the bank account will be quick because the company formation was quick. Companies House registration can complete in days. Bank account approval, particularly with a high street bank and an overseas-based director, routinely takes far longer, and that gap catches out companies that have already committed to a launch date.
The second is continuing to pay UK staff and suppliers via international transfer from an overseas account long after a UK account could have been opened, absorbing unnecessary conversion fees and settlement delays on every payment.
The third is underestimating the documentation banks want, particularly around the source of funds and the company’s ownership structure, which can add real delay if it isn’t prepared and ready before the application starts.
How Paul Beare Helps With This
Paul Beare works with overseas companies across Australia, New Zealand, Canada, the USA and South Africa on exactly this problem, and getting the UK bank account open quickly is consistently one of the most valuable pieces of support we provide. Our UK business bank account service https://www.paulbeare.com/uk-business-bank-account/ guides you through documentation, provider choice and the application itself, and sits alongside our international payroll and payments support https://www.paulbeare.com/international-payroll-payments/ so your banking and payment setup are handled together rather than as two separate problems.
Common questions
Can an overseas company open a UK business bank account without a UK-resident director?
Yes, though high street banks can take several months to approve this. FCA-regulated digital providers are generally faster and now widely accepted for day-to-day UK business banking.
Do I need a UK bank account if I already have a multi-currency account from my home country?
Not strictly for company registration, but in practice most UK clients, suppliers and staff expect payment in sterling from a UK account, and avoiding this adds ongoing cost and friction.
What's the difference between Faster Payments and SWIFT?
Faster Payments handles most domestic UK transfers and typically clears within hours. SWIFT is used for international transfers, generally takes several days, and carries higher fees.
Do Scotland and Northern Ireland use the same currency as England and Wales?
Yes. Sterling is the currency across all four UK nations. Scottish and Northern Irish banks issue their own banknotes, but the currency and its value are identical throughout the UK.